Post‑Labor Economics Series

Get business pricing on tech for your team
- Business-only prices and quantity discounts
- Tax-exempt purchasing
- Multiple users, one account, clear invoices
The Great Decoupling: Can Economies Grow Without Workers?
By Thorsten Meyer – June 2025
1. The paradox in plain sight
The world is making more with fewer hands on the shop‑floor and, increasingly, fewer minds in the back‑office. Global factories ran 4.28 million industrial robots in 2023, a 10 % jump on the prior year, while new installations stayed above the half‑million mark for the third year running. The United States auto sector alone added 13,700 robots in 2024, yet payrolls in vehicle manufacturing were essentially flat. At the same time the global labour share of GDP slid to 52.3 % in 2022, down 0.6 percentage points from the eve of the pandemic.
2. Is the historic GDP–jobs link fracturing?
For most of the 20th century productivity and employment marched upward in loose formation: higher output created new tasks faster than machines displaced old ones. Two new forces claim to break that bond:
| Force | Evidence of acceleration | Why it matters |
| Industrial automation 2.0 | Robot density in South Korea hit 1,012 robots/10 k workers and China vaulted to 470, doubling in four years; the global average is now 162. | Dense automation lets output rise without proportional labour. |
| Generative‑AI at scale | IMF estimates 40 % of jobs worldwide—and 60 % in advanced economies—are “AI‑exposed”. | White‑collar substitution moves “jobless growth” beyond the factory. |
Early macro signs appear in productivity‑rich, labour‑light sectors such as semiconductors, consumer electronics, and software‑as‑a‑service: value added keeps climbing while head‑count stabilises.
3. Where is decoupling already visible?
- South Korea’s electronics cluster is producing record output with employment still below its 2018 peak; firms log robot investments as a hedge against demographic decline.
- U.S. automotive: every 1 % rise in vehicle production since 2022 was matched by only 0.1 % growth in payroll hours, as Tier‑1 suppliers adopt vision‑guided welding cells.
- China’s coastal exporters use automation to offset wage inflation, reaching near‑German robot density levels in less than a decade.
4. Macro‑economic risks of growth without jobs
| Risk channel | Transmission mechanism |
| Demand drag | Fewer wage earners depress household spending; already, consumption represents 68.4 % of U.S. GDP (Q1 2025)—a record high—but is increasingly financed by wealth gains rather than payrolls. |
| Inequality | Capital owners capture automation rents while global labour share erodes. |
| Fiscal strain | Narrower tax base (payroll & VAT) collides with higher outlays for reskilling and social transfers. |
| Political backlash | Regions left behind by automation risk polarisation and anti‑trade sentiment. |
5. Policy playbook for a post‑labour expansion
- Job‑guarantee pilots tied to climate adaptation and elder‑care.
- 32‑hour work‑week trials with overtime sharing to spread remaining labour demand.
- UBI or negative‑income taxes funded by broad VAT plus automation dividends (a surtax on robot‑induced super‑profits).
- Balanced tax codes that equalise effective rates on capital‑deepening and payroll growth.
- Portable benefits & lifelong learning accounts so displaced workers can pivot quickly.
6. Boardroom checklist
| Dimension | Red‑flag metric | Mitigation |
| Revenues | Falling wage‑to‑revenue ratio & slowing unit sales growth | Diversify into premium niches and subscription models |
| Reputation | Media hits on “labour‑light profits” | Publish AI‑impact statements and community investment plans |
| Operational resilience | Supply risk from over‑automation (single‑point failures) | Build “human‑in‑the‑loop” contingency layers |
| Regulatory risk | Emergent robot‑tax or data‑dividend laws | Engage in policy coalitions early |
Dashboard‑Ready Stats (“single‑screen” import)
| Category | Indicator (unit) | Latest level | YoY / Trend | Refresh |
| Automation scale | Operational industrial robots (world) | 4,281,585 units (2023) | +10 % | Annual (IFR) |
| New robot installations (2024 est.) | ≈ 541,000 units | ‑1 % vs 2023 | Semi‑annual | |
| Robot intensity | Robot density – Korea | 1,012 / 10 k workers | +5 % CAGR | Annual |
| Singapore | 770 | Flat | ||
| China | 470 | +17 % YoY | ||
| Germany | 429 | +5 % CAGR | ||
| United States | 295 | +4 % YoY | ||
| Global average | 162 | +7 % YoY | ||
| Sector spotlight | U.S. auto robot installs | 13,700 units (2024) | +10.7 % | Pre‑lim May† |
| Labour share | Global labour share of GDP | 52.3 % (2022) | ‑0.6 pp vs 2019 | Annual (ILO) |
| U.S. compensation share | 51.7 % (2023) | +0.1 pp YoY | BEA/FRED | |
| AI disruption | Jobs “AI‑exposed” | 40 % (global) / 60 % (adv.) | Baseline Jan 2024 | IMF as‑released |
| Consumer demand | PCE share of U.S. GDP | 68.4 % (Q1 2025) | +0.5 pp YoY | Quarterly |
| Household sensitivity | Avg. MPC to permanent income shock | 0.64 | Survey‑based | Annual lit. sweep |
†IFR preliminary result.
Load keys into any BI tool, set alerts when robot installs rise > 5 % and labour share falls in the same period.
Sources (dashboard & text): IFR World Robotics 2024 and related press releases; IMF blog on AI & employment; ILO/FT labour‑share update; U.S. BEA & FRED series; Federal Reserve Survey synthesis on MPC.
7. Scenarios worth modelling
- Profit‑Up / Payroll‑Down – Automation accelerates; consumption weakens; margin resilience hinges on exports and premium pricing.
- Capex Crunch – Recession stalls robot orders; firms that over‑leveraged for automation face balance‑sheet stress.
- Consumer Squeeze – Demand slump forces policy makers into emergency transfers or VAT cuts, raising sovereign‑risk questions.
- Regulatory Brake – Robot‑tax or mandatory “AI impact audits” slow roll‑outs, giving late adopters breathing room.
8. Look ahead
If the 2020s were about proving machines could match cognitive tasks, the 2030s will be about governing an economy where growth no longer guarantees jobs. Whether societies lean toward a Post‑Labour Dividend (shared prosperity via new social contracts) or drift into Algorithmic Capitalism (growth with entrenched inequality) depends on choices made now—by ministers drafting tax codes, by boards allocating capex, and by citizens deciding what kind of prosperity counts.
Thorsten Meyer
Munich & Verona, June 2025
Products Worth Considering
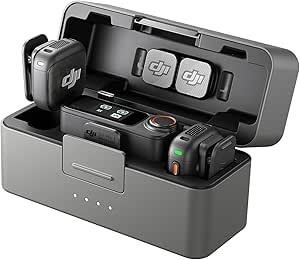
DJI Mic 3 Wireless Microphone System (2 Transmitters, 1 Receiver, Charging Case)

Samsung 27-Inch Odyssey QD-OLED G8 4K 240Hz Gaming Monitor
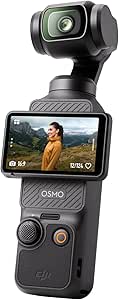
DJI Osmo Pocket 3 Vlogging Camera with 1-Inch CMOS Sensor and 4K Video
As an affiliate, we earn on qualifying purchases.