By Thorsten Meyer | November 1, 2026 | ThorstenMeyerAI.com

Get business pricing on tech for your team
- Business-only prices and quantity discounts
- Tax-exempt purchasing
- Multiple users, one account, clear invoices
A few weeks ago, OpenAI was reportedly asking investors for up to $30 billion. On Friday, 30 October, the story turned. The Financial Times reported that OpenAI had cut its target by $10 billion, to about $20 billion. A few hours later, the Wall Street Journal reported that the company had collected only about $11 billion so far, after a “tepid” response from some large investors. On the same day, S&P Global Ratings changed its outlook on Meta, which S&P itself calls the world’s second-largest digital advertising company, from stable to negative, because of how much it is spending on AI.
Put those two headlines next to each other and it sounds like the money for the AI boom is running out. I checked what is actually confirmed, what is only reported, and what the numbers say when you put them in proportion. My short answer: the money is not running out. It is getting picky. Here is why, where that reading could be wrong, and what it means for companies that buy AI and for the people who use it.
Key takeaways
- The target cut is confirmed by two outlets. The $11 billion is not. The FT reported the cut to about $20 billion, and CNBC confirmed that figure with its own source. The $11 billion comes from the Wall Street Journal alone. OpenAI has not commented, and the round has not closed.
- The valuation slipped, too. The FT and CNBC put it at $1.25 trillion, down from the $1.4 trillion OpenAI first floated. An investor group from the United Arab Emirates is expected to lead, reportedly with an option for OpenAI to rent computing capacity in the region.
- In proportion, this is not a collapse. In March, OpenAI closed $122 billion at an $852 billion valuation, by its own account. What changed is not whether OpenAI can raise money, but on whose terms.
- Meta keeps a top grade, with a warning. S&P affirmed Meta’s AA- rating but turned the outlook negative. Its sharpest line: Meta’s “ability to monetize its AI investments is more limited than that of its peers.” Meta “respectfully” disagrees.
- The cash is visibly tight. Meta’s free cash flow was minus $2.1 billion in the third quarter, against plus $10.6 billion a year earlier, as it guided to $135 to $145 billion of capital spending this year.
- For companies and users, the risk is not a sudden shutdown. It is a slow change in prices, limits and contract terms. Treat AI providers like any critical supplier, and keep a plan B.
Products Worth Considering

Samsung 27-Inch Odyssey QD-OLED G8 4K 240Hz Gaming Monitor

Amazon Kindle Paperwhite (12th Generation, 2024), 16 GB, 7-inch Display, Jade
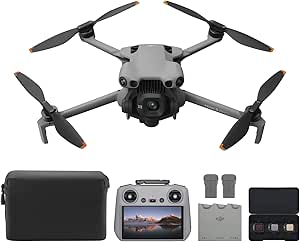
DJI Mini 5 Pro Fly More Combo Plus with DJI RC 2
As an affiliate, we earn on qualifying purchases.
What was reported, and what is actually confirmed
This story rests on reporting, not on company announcements, so the source of each number matters. Here is the state of play as of Saturday, 31 October.
- The cut (two outlets). The Financial Times reported on Friday, citing people with knowledge of the matter, that OpenAI cut its target by $10 billion and now seeks about $20 billion. Reuters relayed the report but did not confirm it independently. On Saturday, CNBC said it had confirmed the $20 billion figure with a person directly familiar with the deal, who stressed that the round is still in progress and the numbers could change.
- The valuation (two outlets). Both the FT and CNBC put the valuation at $1.25 trillion, down from the $1.4 trillion first floated. CNBC wrote on 22 October that $1.25 trillion was the value before the new money. On 31 October it cited the FT describing it as the value after the new money. If both are right, the price per share slipped once more. That is my reading of two reports, not a confirmed fact.
- The deadline and the first close (one outlet). According to the FT, OpenAI gave investors until Friday to commit, some reduced their allocations, and the “first close” is expected to raise less than $20 billion. A later offering to wealthy individuals at the same valuation could fill the gap.
- The investors (one outlet, partly two). The FT reported that a consortium of UAE investors, including the state-backed fund MGX, is expected to be the largest participant, and that OpenAI would gain an option to lease new computing capacity in the region. Founders Fund, Coatue, Sequoia Capital and Andreessen Horowitz are also expected to take part. CNBC had reported on 22 October that UAE investors and Coatue lead the round.
- The $11 billion (one outlet). The Wall Street Journal reported that OpenAI has secured about $11 billion so far and met a “tepid” response from some large investors. TechCrunch, The Decoder and Investing.com repeated the figure, all citing the Journal. I found no second outlet that confirmed it independently.
- OpenAI (no comment). OpenAI did not respond to requests from Reuters, CNBC or TechCrunch, and its website carries no statement on the round.
Infographic 01 · Confirmed or only reported
What we know about OpenAI’s shrinking round
Every number in this story comes from reporting, not from OpenAI. Here is which claim rests on how many sources.
- Target cut by $10B to about $20BTwo outlets
FT, citing people with knowledge of the matter; CNBC confirmed the figure with its own source. Round still open.
- Valuation $1.25T, down from $1.4TTwo outlets
FT and CNBC. Before or after the new money? The two CNBC reports differ.
- Friday deadline, first close below $20BOne outlet
FT. A later offering to wealthy individuals could fill the gap.
- UAE group with MGX expected to lead, option to lease computing capacityOne outlet
FT. CNBC had reported UAE investors and Coatue as leads on 22 Oct.
- About $11B secured, “tepid” response from some big investorsOne outlet
Wall Street Journal. Repeated by others, confirmed by none.
- OpenAINo comment
No reply to Reuters, CNBC or TechCrunch. No statement on its website.
How the round shrank
- 31 Mar 2026$122B closed at an $852B valuationOpenAI’s own announcement
- 22 Oct 2026Up to $30B at $1.25T, before new moneyCNBC, people familiar with the deal
- 30 Oct 2026Target cut to about $20BFT, relayed by Reuters
- 30 Oct 2026About $11B collected so farWall Street Journal
- 31 Oct 2026$20B confirmed, round not closedCNBC
“Two outlets” means two news organizations reported it with their own sources. None of this is confirmed by OpenAI.
Sources: FT via Reuters, 30 Oct 2026, CNBC, 31 Oct 2026, CNBC, 22 Oct 2026, WSJ as reported by Investing.com, 31 Oct 2026, OpenAI, 31 Mar 2026.
Powered by Thorsten Meyer AI
Why $11 billion is not a collapse
Eleven billion dollars only looks small next to OpenAI’s last round. On 31 March, OpenAI announced that it had closed “$122 billion in committed capital at a post money valuation of $852 billion,” including more than $3 billion from individual investors through banks. It also expanded an undrawn credit line to about $4.7 billion. At the time, OpenAI said it was generating $2 billion in revenue per month.
So why raise again so soon? Because the bills are enormous. CNBC reported in October that OpenAI told investors in February it is targeting roughly $600 billion of total computing spend by 2030. CNBC also described the new round as an “opportunistic” bridge ahead of a possible stock market listing. OpenAI’s finance chief told employees in August that the company “will be a public company in 2027,” according to CNBC.
Think of a house that sold in a hot market last spring. This autumn, the same house is still worth a lot. But buyers want a discount, they take their time, and some of them bring conditions. That is what the reports describe: a lower valuation, slower commitments, and a lead investor that reportedly wants a computing deal attached. Money with strings is still money. It is just not a blank check.
There is a second pressure that has nothing to do with the economy: competition for the same investors. Reuters has reported that OpenAI wanted to close this round partly to get ahead of Anthropic’s expected stock market listing, because the two are tapping a similar investor base. The Wall Street Journal also reported, citing figures it had seen, that Anthropic’s quarterly revenue has recently grown faster than OpenAI’s. That claim comes from one outlet. I covered what is confirmed about Anthropic’s plans in Anthropic could go public with a “junk” credit rating.
Meta: the AA- company S&P is worried about
The second headline is about a very different company. Meta does not need venture capital. It earns most of its money from advertising, and S&P still rates its debt AA-, one of the highest grades any company has. On 30 October, S&P kept that rating but changed the outlook from stable to negative. An outlook is not a downgrade. It is a signal of which way the rating could move if things do not change.
S&P’s research update is behind a paywall. Reuters, CNBC and the trade site PPC Land quoted it at length, and their quotes match. The core of it, in plain words:
- Spending. “Given the lack of clarity around the company’s future capex and its very ambitious multi-year AI investment plans, we are less certain that it will curtail its spending as previously anticipated,” S&P wrote, as quoted by Reuters.
- Earning it back. “Meta’s ability to monetize its AI investments is more limited than that of its peers,” S&P said. The contrast it draws, as quoted by PPC Land: several peers already rent out their data center capacity to other companies, including AI labs. Meta mostly uses its own.
- Debt. S&P measures leverage as debt, including leases, divided by yearly operating earnings before depreciation. It put Meta at about 0.1 times in 2025 and said the figure could rise above its 1.0 threshold for the AA- rating as early as 2027, mainly because of data center leases rather than bonds.
- Cash. According to PPC Land and 24/7 Wall St, which both quote the report, S&P now expects Meta’s free operating cash flow to be negative in 2026, 2027 and 2028, with the deficit peaking at about $71 billion in 2027.
Meta’s own numbers explain the worry. Its third-quarter results, published on 21 October, show capital spending, including principal payments on finance leases, of $34.91 billion in the quarter and free cash flow of minus $2.12 billion, against plus $10.63 billion a year earlier. Meta expects $135 to $145 billion of capital spending for 2026. Its quarterly filing lists about $355.73 billion of data center and other leases that have been signed but not yet started, running through 2036 with terms of up to 30 years. That is the number behind S&P’s leverage forecast. I explained how those leases work in Who pays for the AI data center boom?.
Meta pushed back. “We respectfully disagree with S&P’s assertion about Meta’s AI monetization capabilities,” a spokesperson told Reuters and CNBC. “We see significant product and business opportunities ahead of us, supporting our very strong credit profile.” Meta has also just raised $37.5 billion in new stock and preferred shares, and plans a further stock sale program of up to $60 billion from early 2027, as I described in How Big Tech now pays for AI. According to PPC Land’s reading of the report, S&P calls that raise “credit positive,” but does not count the future $60 billion program in its forecast.
Infographic 02 · Meta through S&P’s eyes
A top grade with a warning attached
S&P kept Meta’s AA− rating but turned the outlook negative. The reason is not the ad business. It is the gap between AI spending and AI revenue.
Monetization is the weak spot
“Meta’s ability to monetize its AI investments is more limited than that of its peers.” Peers already rent data center capacity to others; Meta mostly uses its own.
“We respectfully disagree”
Meta sees “significant product and business opportunities ahead of us, supporting our very strong credit profile.” It just raised $37.5B in new stock and preferred shares.
Leverage: debt incl. leases ÷ yearly earnings
S&P-adjusted, as quoted
Capital spending, S&P forecast
As quoted by PPC Land and 24/7 Wall St
S&P’s research update is subscriber-only. Quotes and forecasts come from Reuters, CNBC, PPC Land and 24/7 Wall St. Bars are scaled within each card. An outlook is not a downgrade.
Sources: S&P via Reuters, 30 Oct 2026, CNBC, 30 Oct 2026, PPC Land, 24/7 Wall St, Meta Q3 2026 results, Meta Form 10-Q.
Powered by Thorsten Meyer AI
One week, one question
These two stories did not happen in a vacuum. In the same week:
- S&P lowered Broadcom’s outlook to stable from positive on 29 October, saying the chipmaker’s rapid AI growth increases its exposure to a few big customers (Reuters). Earlier this year, S&P cut Oracle to BBB-, one notch above “junk,” citing its heavily leveraged balance sheet.
- The FT reported that Anthropic could get a “junk” credit rating after its listing. No agency has rated it yet.
- Intel had its worst trading day in decades after a weak forecast. Details in Intel’s worst day since the 1970s.
- The US economy leaned on AI. Information processing equipment and software added about a third of third-quarter growth, as I showed in What happens if the AI boom slows?.
None of this is new information about whether AI works. It is investors and lenders asking, all at once, the question they skipped for two years: when does this pay off? S&P put it on record in August, two months before the Meta decision. Its report on AI and the biggest cloud and platform companies expects all six it covers, Alphabet, Amazon, Microsoft, Meta, Oracle and SpaceX, “to generate negative free operating cash flow in 2026 and 2027 with recovery not projected until 2029.” Its models “generally assume a 2028 inflection point.” Lenders are now watching whether that inflection arrives on time.
Running out, or getting pickier?
Here is the case for “running out”: a flagship AI company cut its target by a third, reportedly found big investors reluctant, and had to set a deadline. A company with one of the best credit ratings in the world was warned about its AI spending. And markets were nervous: the Nasdaq fell 2.9% on Friday and closed 7.8% below its 6 October record high, Reuters reported.
Here is the case for “getting pickier”: even the reported low figure, $11 billion in a few weeks, is a very large amount of money, and the round is not over. Meta raised $37.5 billion of equity in a single week. S&P did not downgrade anyone in this story. And the investors who are still writing checks are asking for something in return, such as computing deals, lower prices and a path to profit.
My reading, as opinion: pickier. Capital has not left AI. It has started to price risk. That means a lower valuation for OpenAI, a warning instead of a downgrade for Meta, and higher costs of money for weaker players. One funding round is not a crash. A negative outlook is not a downgrade. Where this reading could be wrong: if the first close comes in well below the reported figures, if the retail offering fails, or if Meta’s 2027 spending plan is higher than S&P already assumes, “picky” can turn into “scarce” quickly.
Infographic 03 · Running out or picky?
The AI money is not gone. It asks harder questions.
The evidence on both sides, the question lenders now ask, and what it means in practice.
Signs of “running out”
- OpenAI’s target cut by a third, to about $20B (FT, CNBC).
- “Tepid” response from some large investors (WSJ).
- S&P turns Meta’s outlook negative and lowers Broadcom’s to stable.
- Nasdaq 7.8% below its 6 Oct record high on 30 Oct (Reuters).
Signs of “getting picky”
- Even the reported $11B is a lot of money, and the round is still open.
- Meta raised $37.5B of equity in one week. S&P downgraded no one here.
- Investors attach conditions: lower valuation, a computing deal, a path to profit.
- OpenAI closed $122B in March, by its own account.
What it means
Supplier risk
Check how your AI provider is financed, keep a second model tested, lock prices and data export in the contract.
Limits before shutdowns
Expect tighter free tiers and changed limits, not sudden closures. Export your data, prefer monthly plans.
Three dates
OpenAI’s first close. Anthropic’s listing. Meta’s 2027 spending guidance with its Q4 results.
My reading, as opinion: pickier, not empty. One funding round is not a crash, and a negative outlook is not a downgrade. Not investment advice.
Sources: FT via Reuters, 30 Oct 2026, CNBC, 31 Oct 2026, WSJ as reported by Investing.com, 31 Oct 2026, S&P via Reuters, 30 Oct 2026, S&P Global Ratings, 27 Aug 2026, OpenAI, 31 Mar 2026.
Powered by Thorsten Meyer AI
What this means for companies
- Treat your AI provider like any critical supplier. Ask how it is financed and how long its money lasts. Private AI labs publish little, so watch the signals: funding news, price changes, sudden changes to terms.
- Keep a second provider tested and ready. Build your applications so that switching models is a configuration change, not a rewrite. Run your important tasks against a second model every quarter.
- Negotiate the boring parts of the contract. Price protection for 12 months, notice periods before price or limit changes, data export in a usable format, and what happens if a product or model is discontinued.
- Budget for higher prices later. Right now, competition pushes prices down; the WSJ reported that OpenAI cut prices on its newest models. When investors start to demand profits, discounts tend to end first.
- If you sell to AI labs or hyperscalers, watch your customer concentration. That was S&P’s point about Broadcom.
What this means for users
- Expect changes in limits and plans before you see a shutdown. Nothing in these reports suggests that ChatGPT or Meta’s AI products are at risk. The more likely effects are tighter free tiers, changed limits and new paid plans. For an example of how fast limits change, see OpenAI doubles ChatGPT Pro limits.
- Keep your own copies. Export important chats, files and custom instructions regularly.
- Prefer monthly billing for tools you cannot easily replace, unless the annual discount is worth the risk to you.
- Remember that you may already be an investor. Pensions and index funds hold the big tech companies. That is not advice, just something to know.
Limits of this analysis
- The OpenAI figures come from people familiar with the deal, not from the company. The round is open, and the numbers can change.
- The $11 billion figure has one source, the Wall Street Journal. I could not read the Journal or the FT directly and rely on how other outlets reported them.
- I could not access S&P’s full research update. Its quotes here come from Reuters, CNBC, PPC Land and 24/7 Wall St. Reuters reported a 2026 cash flow deficit of $39 billion, while PPC Land and 24/7 Wall St report $22 billion for 2026 and $39 billion for 2028. I use only the 2027 figure, on which all three agree.
- Valuations of private companies are negotiated prices, not market prices.
- Nothing here is investment advice. I make no forecast for any stock or bond.
What to watch next
- Whether OpenAI announces a first close, and at what amount and valuation.
- Anthropic’s listing, which Reuters calls imminent and the WSJ reported is expected in November, and how investors price it.
- Meta’s 2027 spending guidance, expected with its fourth-quarter results.
- Further rating actions on AI-heavy companies, from S&P and others.
Sources
Financial Times, OpenAI slashes funding target by $10bn (30 October 2026), as relayed by Reuters via Business Recorder (30 October 2026).
CNBC, OpenAI pares fundraising goal, now seeking up to $20 billion in latest round (31 October 2026); OpenAI nears up to $30 billion funding round at $1.25 trillion valuation led by UAE investors (22 October 2026).
Wall Street Journal, OpenAI Raises Less Than Half of $30 Billion Target in Latest Round (30 October 2026), as reported by Investing.com, TechCrunch and The Decoder (31 October 2026).
OpenAI, OpenAI raises $122 billion to accelerate the next phase of AI (31 March 2026).
S&P Global Ratings, research update “Meta Platforms Inc. Outlook Revised To Negative On Significant Uncertainty Around Capex And Free Operating Cash Flow” (30 October 2026, subscriber access), as reported by Reuters via Lufkin Daily News, CNBC (30 October 2026), PPC Land and 24/7 Wall St (31 October 2026).
S&P Global Ratings, AI Infrastructure Investment To Exceed $1.3 Trillion By 2027 (27 August 2026).
Meta Platforms, Q3 2026 results (21 October 2026) and Form 10-Q (22 October 2026).
Media reports are marked as reported. Company and agency statements are quoted as their claims. Nothing here is investment advice.
Researched and drafted with AI assistance, including Anthropic’s Claude.